What a rare CIDRA decision says about online proposal forms, property condition and the duty to answer accurately.
Online insurance forms are designed around standard answers. But what happens when a policyholder says none of the options quite fits? In Rohatgi v AXA Insurance UK Plc [2026], the court placed the responsibility firmly on the applicant to answer accurately or ask the insurer for clarity.
A customer cannot safely choose an inaccurate answer simply because it appears to be the closest option. If no answer reflects the true position, the safer course is to contact the insurer.
The dispute followed a fire at Mr Rohatgi’s property. After investigating the claim, AXA avoided the policy on the basis of three alleged misrepresentations made when the cover was arranged online:
Mr Rohatgi denied making misrepresentations. His central argument was that the online questions were not sufficiently clear and, on occupancy, that none of the available choices captured his particular circumstances. He said he had selected the closest available option.
The court found the online application process clear and unambiguous.
The occupancy menu catered for the situations most customers were likely to encounter. Crucially, a customer who could not identify a suitable category was not entitled simply to select an answer that did not reflect the true position. The customer could instead have contacted the insurer for guidance.
On the facts, Mr Rohatgi had not lived at the property permanently or regularly, and the occupancy answer he gave was inaccurate.
“Good state of repair” means more than structural soundness
The condition of the property produced a second important point in respect of what should be considered to be "a good state of repair".
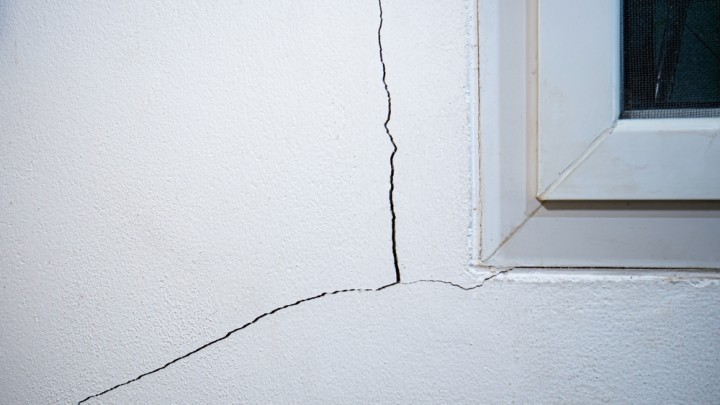
Mr Rohatgi argued that the required works were cosmetic and that the building remained structurally sound. The court rejected the suggestion that “good state of repair” was confined to the external structure.
The assessment also extended to the general condition of internal features, including ceilings and plasterwork. Having considered the evidence, the court found that the property was neither in a good state of repair nor habitable. The answer given to AXA was therefore a misrepresentation.
Mr Rohatgi also maintained that he, rather than his former insurer, had ended the previous cover because he had stopped paying the premium. The court accepted that the previous insurer had cancelled the policy for non-payment. Consequently, Mr Rohatgi's representation to AXA about prior cancellation was therefore also inaccurate.
Mr Rohatgi pointed to an alternative product that could provide insurance and was also underwritten by AXA. The court declined to place weight on that comparison based on the facts of this case. The alternative product was offered by a different company and operated under different terms, premiums and underwriting guidelines.
| Audience | Lesson | Practical significance |
| For insurers | Clarity still matters | Online questions and declarations should be clear, unambiguous and directed to the information the insurer needs. Standardised answer sets may be acceptable where they cover the common situations and customers can seek guidance. |
| For property risks | Condition is assessed broadly | A property may fail the “good state of repair” test even if its structure is sound. Internal condition and habitability can also be relevant. |
Rohatgi is a useful illustration of how the Consumer Insurance (Disclosure and Representations) Act 2012 may operate in an online sales journey. Digital convenience does not remove the consumer’s duty to take reasonable care. At the same time, the decision underlines the importance of carefully framed questions and a route for customers to obtain help when their circumstances do not fit a standard answer.
For insurers, the judgment offers reassurance that a well-designed online process can support a misrepresentation case.
This successful outcome demonstrates our use of a robust evidential strategy, including the use of expert and witness evidence. Our role in distilling complex evidence into a compelling case and persuasively advancing it at trial was instrumental in securing the judgment in AXA’s favour.
Designed to elevate the policyholder experience and empower handlers, ClaimPilot transforms the claims journey with state-of-the-art AI, streamlined processes and reduced operational bottlenecks – all in one powerful platform.